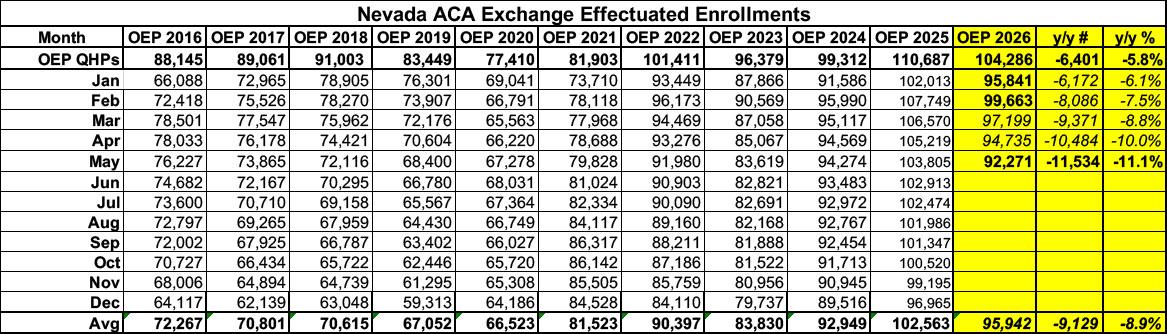
ACA exchange enrollment has dropped by 11% in Nevada since Congressional Republicans allowed the enhanced federal subsidies to expire at the end of last year.
Initial signups during Open Enrollment were only down ~6% vs. OEP 2025...but effectuated enrollment has gradually shrunk further every month since then and stood at 11.1% lower as of May 2026.
That's over 11,000 Nevadans who have lost coverage so far this year.
Here's what this looks like visually, with both 2025 and 2019 (the last pre-COVID year, which didn't include the enhanced subsidies) included for comparison:
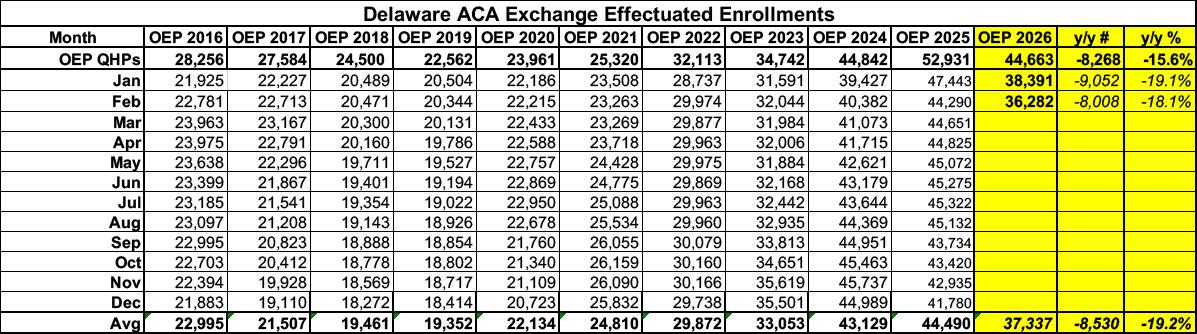
ACA exchange enrollment has dropped by 18% in Delaware since Congressional Republicans allowed the enhanced federal subsidies to expire at the end of last year.
Initial signups during Open Enrollment were already down over 15% vs. OEP 2025...and effectuated enrollment has continued to slip to the point that it was 18% lower in February 2026 than a year earlier.
Here's what this looks like visually, with both 2025 and 2019 (the last pre-COVID year, which didn't include the enhanced subsidies) included for comparison:
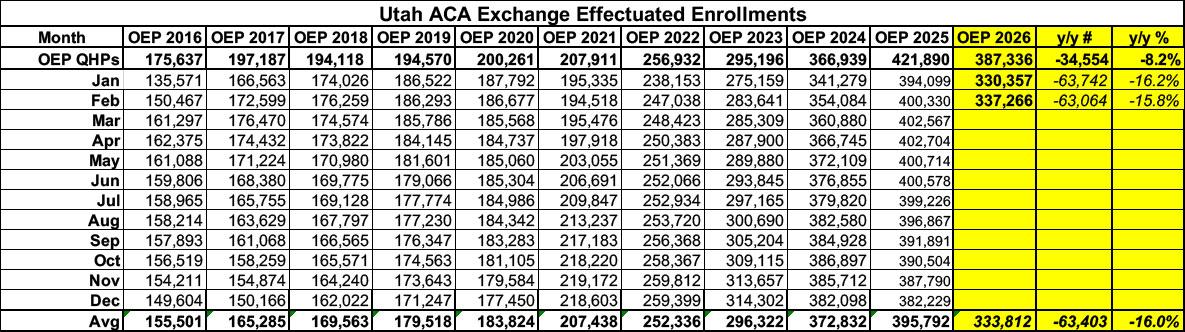
ACA exchange enrollment has dropped by 16% in Utah since Congressional Republicans allowed the enhanced federal subsidies to expire at the end of last year.
Initial signups during Open Enrollment were down 8% vs. OEP 2025...but the drop in effectuated enrollmentdoubled in the first two months of the year, to around 16% lower vs. the same point a year earlier.
That's over 63,000 Utahns who already lost coverage in just the first two months...a number which has likely continued to climb since then.
Here's what this looks like visually, with both 2025 and 2019 (the last pre-COVID year, which didn't include the enhanced subsidies) included for comparison:
Before I begin, it's important to note that ACA exchange enrollment has dropped in Hawaii since Congressional Republicans allowed the enhanced federal subsidies to expire at the end of last year. Fortunately, the raw number of enrollees who have lost coverage is pretty small due to:
a) Hawaii only having around 1.4 million residents to begin with and
b) Hawaii having a much more robust Employer-Sponsored Health Insurance mandate law than the ACA. Under the Hawaii Prepaid Health Care Act of 1974, employers are required to offer coverage to employees working at least 20 hours per week. In contrast, the federal Patient Protection and Affordable Care Act requires employers to offer coverage to employees working at least 30 hours per week.
As a result, Hawaii's individual/nongroup health insurance market is smaller as a percentage of the total population than it is in most other states.
RETURNING BIDEN OVERCHARGES TO WORKING FAMILIES: Today, President Donald J. Trump announced that the federal government will return to the American people hundreds of millions in Obamacare overcharges, collected by the Biden Administration, by issuing refunds of $500 per person to nearly 1 million Americans in 30 states. Today’s actions directly refund the Americans most exposed to the higher costs imposed by the Biden Administration’s gross mismanagement of Obamacare.
So what the hell is this all about? Let's take a look, shall we?
Thirteen health insurers request average 22.4% rate increase for 2027 individual market
OLYMPIA, Wash. — Thirteen health insurance companies have requested an average rate change of 22.4% for Washington state’s 2027 individual health insurance market. Insurers base requested rate changes on assumptions made about the services their policyholders will use and the cost to deliver that care.
“I know the requested rate changes will be difficult for individuals and families,” said Insurance Commissioner Patty Kuderer. “We’re going to spend the next several months reviewing every assumption made by the insurers to make sure their requests are justified.”
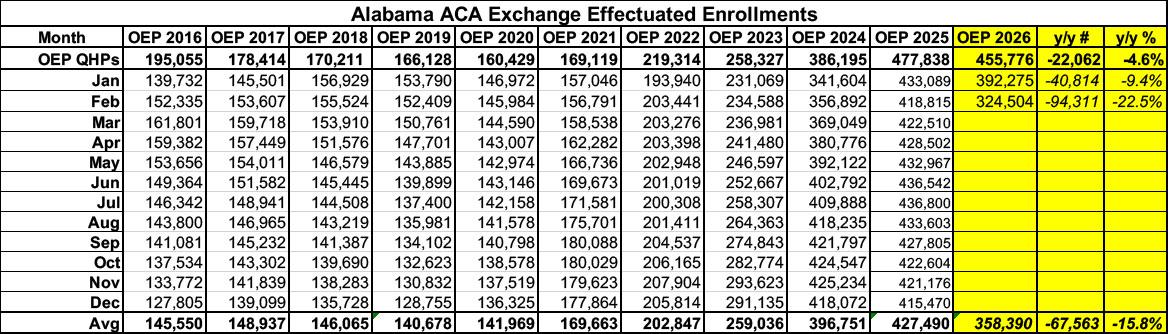
ACA exchange enrollment has dropped by nearly 23% in Alabama since Congressional Republicans allowed the enhanced federal subsidies to expire at the end of last year.
Initial signups during Open Enrollment were already down 4.6% vs. OEP 2025...buteffectuated enrollment as of January 2026 was down over 9% year over year...increasing to a 22.5% drop as of February.
That's over 94,000 Alabamans who already lost coverage in just the first two months of the year...a number which has likely continued to climb since then.
Health insurers must make an application to the Department of Financial Services to evaluate their proposed rate changes. The Department reviews the rate applications along with the insurer’s underlying calculations to make sure that rate increases are justified and not excessive. During review, DFS may request more information from the insurer and consider comments from policyholders or the public. Rate applications and all documents relating to an application can be found here:
Individual and Small Group Medical Premium Rates
Beginning with rate application filings submitted in 2023 for benefit year 2024, rate information will be contained in one place for all insurers, separated by Market Segment.
Thanks to New Mexico backfilling 100% of ALL lost federal tax credits for EVERY ACA exchange enrollee in the state who was eligible for subsidies last year, their average monthly enrollment total is actually higher than it was in 2025 in spite of Congressional Republicans allowing the enhanced federal subsidies to expire at the end of 2025. Initial signups during Open Enrollment were actually up a whopping 18% vs. OEP 2025.
Even so, effectuated enrollment has still gradually declined over the course of the year so far...from 15% higher year over year in January to just 0.5% higher as of July...and this month it actually slipped slightly below the August 2025 tally (New Mexico is one of a handful of states which provide timely, monthly effectuated enrollment data reports).
CONNECTICUT INSURANCE DEPARTMENT RELEASES HEALTH INSURANCE RATE REQUEST FILINGS FOR 2027
The Connecticut Insurance Department (CID) has received rate filings from four health insurers for plans to be offered in the individual and small group markets, both on and off the state-sponsored exchange, Access Health CT . As part of CID’s statutory responsibilities, the CID will conduct a thorough and careful review of each filing to ensure compliance with Connecticut insurance laws and regulations.
The CID’s review process will examine each submission in detail, requiring insurers to provide justifications and supporting evidence for their requested rates. All filings are available on the CID’s website .